Squeeze Setups
A live squeeze scanner built around the Slingshot Squeeze, with 22 years of backtest results behind it.
See it, $99/month →
All Backtesters
Part of TTM Squeeze →
Beginner-Friendly
33 mins
TTM Squeeze Histogram Backtester for ThinkorSwim
A free Squeeze histogram backtester for ThinkorSwim: it trades the first yellow bar after 7 red, or the first blue after 7 cyan, with an RSI filter.
Download Backtester
Table of Contents
- Key Takeaways
- The Four Colors of the Squeeze Histogram
- What a Momentum Shift Looks Like
- The Trading Rules
- How to Create the Backtester in ThinkorSwim
- The Inputs
- How the Code Works
- How to Read the Results
- Free Version vs Member Version
- Results From the Video
- How I Use the Backtester
- Related Squeeze Backtesters and Tools
- Common Problems
In this tutorial I build a Squeeze histogram backtester for ThinkorSwim to answer one question: is the histogram useful for catching momentum swings? It goes long on the first yellow bar after 7 red histogram bars in a row, goes short on the first blue bar after 7 cyan bars, and exits at the first sign the momentum is fading.
It’s a strategy, so ThinkorSwim totals the profit and loss on whatever chart and timeframe you load. An RSI filter cuts some of the noise, and inputs change the bar count, the RSI levels and which sides it trades. It’s for Squeeze traders who read the histogram and want to test it first.
Key Takeaways
- The Squeeze histogram backtester is a free ThinkorSwim strategy that tests whether a change in histogram color times a momentum shift.
- It goes long on the first yellow bar after 7 red histogram bars in a row when the RSI is below 40, and short on the first blue bar after 7 cyan bars when the RSI is above 60.
- A long trade exits at the close of the first bar where the histogram is lower than the bar before. A short trade exits at the close of the first bar where it’s higher.
- It has 5 inputs: consecutiveHistogramBars (7), RSIOverboughtVal (60), RSIOversoldVal (40), longEntries (yes) and shortEntries (yes).
- In the video, the members’ version showed 12 winners and 32 losers on the long side and 17 winners and 23 losers on the short side, on a 5-minute S&P chart over 30 days.
The Four Colors of the Squeeze Histogram
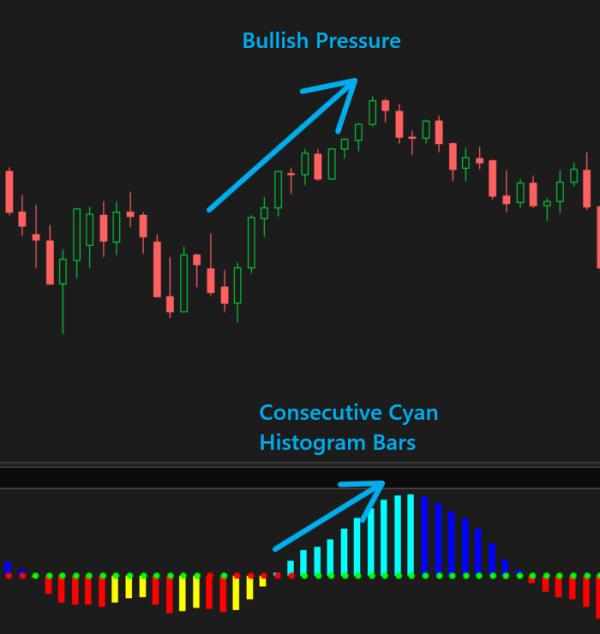
The Squeeze histogram is the bar plot of ThinkorSwim’s free built-in Squeeze study, and each bar is one of 4 colors. The color comes from two checks: is the bar above or below zero, and is it higher or lower than the bar before it?
The study’s other output, the dots, tells you whether there’s a squeeze. This backtester ignores the dots and works only with the histogram. Our Squeeze hub covers the dots, and the MTF Squeeze indicator shows them for many timeframes at once.
| Color | Zero line | Compared with the previous bar | What it says about momentum |
|---|---|---|---|
| Cyan | Above 0 | Higher | Bullish momentum is increasing |
| Blue | Above 0 | Lower | Bullish momentum is fading |
| Red | Below 0 | Lower | Bearish momentum is increasing |
| Yellow | Below 0 | Higher | Bearish momentum is fading |
What a Momentum Shift Looks Like
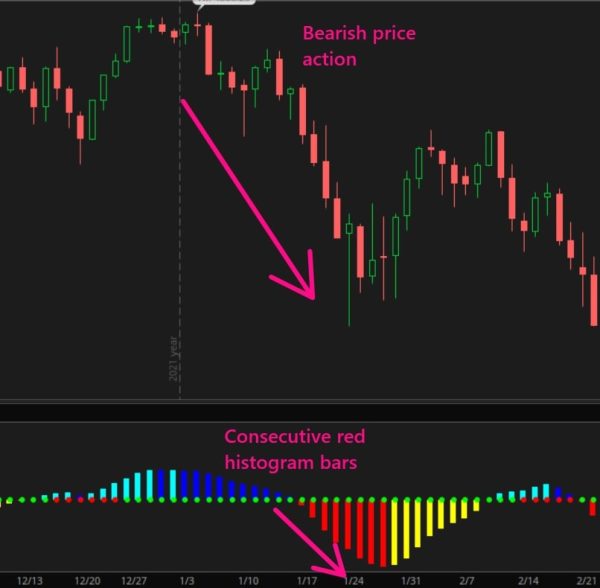
A momentum shift on the Squeeze histogram is the first bar of a new color after a long run of one color. The goal of this tutorial is to test whether those turning points are useful for catching momentum swings.
- Bullish shift. 7 red bars in a row say momentum is declining. The first yellow bar after them is the sign of at least a temporary bullish shift.
- Bearish shift. 7 cyan bars in a row mark a bullish move. The first blue bar says momentum is shifting into at least a temporary pause, if not a shorter-term pullback.
The first example in the video is a bullish trade on the S&P 500. The histogram printed more than 7 red bars, then its first yellow bar, and the backtester bought there. It rode the move as the bars kept rising through zero and sold on the first blue bar, the first sign the momentum was stalling.
The Trading Rules
The Squeeze histogram backtester has two entry conditions, one bullish and one bearish, and each depends on the run of bars that came before. Every entry and exit uses the closing price of the bar where its condition is true.
| Rule | Long trade | Short trade |
|---|---|---|
| Setup | 7 red bars in a row, ending on the previous bar | 7 cyan bars in a row, ending on the previous bar |
| Trigger bar | Yellow | Blue |
| RSI filter | RSI below 40 (oversold) | RSI above 60 (overbought) |
| Entry | Buy to open at the close | Sell to open at the close |
| Exit | Sell to close at the close of the first bar where the histogram is lower than the bar before | Buy to close at the close of the first bar where the histogram is higher than the bar before |
| On/off switch | longEntries |
shortEntries |
The exit tries to ride the momentum for as long as possible. Read the code closely, though: the long exit fires on the first lower bar of any color. If a yellow bar is followed by a red one, the trade closes there, below zero, without waiting for a blue bar.
How to Create the Backtester in ThinkorSwim
The Squeeze histogram backtester is a strategy, so you create it from the Strategies tab. That step is very important: only a strategy can place the simulated orders that produce a profit and loss report.
- Click the Studies icon at the top of your chart.
- Switch over to the Strategies tab and click Create.
- Give the backtester a name. I called mine TI_SqueezeHistogram_Backtester, the name the download uses.
- Leave the default
AddOrderline in the editor while you build, so you don’t get an error right away. - Write the code in the steps below, or paste the finished code from the Code tab, then click OK and Apply.
The download is the same code as a .ts strategy file. If you’d rather import it, our guide on how to import a file into ThinkorSwim covers the steps.
The Inputs
The Squeeze histogram backtester has 5 inputs. Double-click the backtester on your chart to change any of them from the studies menu instead of editing the code.
input consecutiveHistogramBars = 7;
input RSIOverboughtVal = 60;
input RSIOversoldVal = 40;
input longEntries = yes;
input shortEntries = yes;
The table explains what each one controls.
| Input | Default | What it controls |
|---|---|---|
consecutiveHistogramBars |
7 | How many cyan or red bars in a row come before the shift |
RSIOverboughtVal |
60 | The RSI has to be above this for a short entry |
RSIOversoldVal |
40 | The RSI has to be below this for a long entry |
longEntries |
yes | Turns long trades on or off |
shortEntries |
yes | Turns short trades on or off |
How the Code Works
The Squeeze histogram backtester code has 6 parts, written in the order below. I tested each one on the chart before moving on, and the snippets are copied from the download.
Step 1: Reference the Histogram
The most basic piece is the histogram itself, brought over from the built-in Squeeze study.
def histogram = TTM_Squeeze().histogram;The name before the dot is the study, and histogram after it picks the plot. One line, and the strategy can read every histogram bar.
Step 2: Define the Four Colors
Splitting the histogram into its 4 colors makes the rest of the code much easier to write.
#Cyan, Blue, Yellow and Red Histogram Bar Definitions
def cyan = histogram > histogram[1] and histogram > 0;
def blue = histogram < histogram[1] and histogram > 0;
def red = histogram < histogram[1] and histogram < 0;
def yellow = histogram > histogram[1] and histogram < 0;
Each line is the color table above written in thinkScript. histogram[1] is the previous bar’s value.
To test the color definitions, I added a label that prints one of them. On a chart whose last bar was red, it showed 1. After I swapped red for cyan, it showed 0. That’s a test line from the video and isn’t in the download:
AddLabel(yes, red, Color.YELLOW);Our AddLabel tutorial covers labels in more depth.
Step 3: Count the Consecutive Bars
The setup needs a run of cyan bars or red bars, and the Sum function counts them.
#Consecutive Momentum Histogram Bars
def minCyanBars = Sum(cyan, consecutiveHistogramBars) >= consecutiveHistogramBars;
def minRedBars = Sum(red, consecutiveHistogramBars) >= consecutiveHistogramBars;
A cyan bar is 1 and any other bar is 0. If the sum over the last 7 bars is at least 7, all 7 were cyan.
I tested it with a yellow chart bubble. The first bubble appeared on the 7th cyan bar in a row, and bubbles kept plotting on every bar after it until the first blue bar.
Step 4: Find the Momentum Shift
#Momentum Shifts in Histogram
def momoDown = minCyanBars[1] and blue;
def momoUp = minRedBars[1] and yellow;
momoDown needs 7 cyan bars that were true on the previous bar and a blue bar now. momoUp needs 7 red bars on the previous bar and a yellow bar now.
The bubbles landed on the first bar of the new color, as expected. One of them was a false signal: momentum turned back up about 2 bars later. Filtering signals like that is the next step.
Step 5: Add an RSI Filter
The RSI filter tries to cut false signals by asking whether the market is overbought or oversold. You can use any indicator you like here. I used the built-in RSI to keep things simple.
#RSI
def RSIOverbought = RSI() > RSIOverboughtVal;
def RSIOversold = RSI() < RSIOversoldVal;
RSI() with empty parentheses uses the built-in study’s default settings, a 14-period RSI. The 60 and 40 thresholds sit closer to 50 than the 70 and 30 lines the RSI study draws.
On a daily SPY chart in the video, adding the oversold filter to the bullish shifts removed a few bubbles on the left and quite a few on the right. Then I turned the hard-coded 60, 40 and 7 into inputs.
Step 6: Place the Orders
AddOrder is the function that places the simulated trades, and it’s the bulk of how a backtester works.
AddOrder(OrderType.Buy_To_Open, longEntries and momoUp and RSIOversold, close);
AddOrder(OrderType.Sell_To_Close, histogram < histogram[1], close);

AddOrder(OrderType.Sell_To_Open, shortEntries and momoDown and RSIOverbought, close);
AddOrder(OrderType.Buy_To_Close, histogram > histogram[1], close);
The buy order fires on a bullish shift in oversold territory, and the sell-to-close fires on the first lower histogram bar. The short side mirrors it with sell to open and buy to close.
The longEntries and shortEntries inputs went in last, so you can see which side contributes to the P&L. These AddOrder lines don’t set a trade size, so ThinkorSwim uses the default trade size from Global Strategy Settings.
How to Read the Results
ThinkorSwim marks each of the backtester’s orders on the chart (pink text in the video) and draws its running profit and loss in a floating P&L graph under the price. If you don’t see the graph, open Global Strategy Settings and turn on Display floating P&L with strategies.
For the trade list, right-click the strategy on the chart and choose Show report. In the video, I checked the most recent trade that way. It was a short opened on a blue bar, the histogram rose on the very next bar, and the report listed it as a loser, as expected.
The report gets harder to use as the sample grows. On 5 days of data it’s manageable, but 30 days gives many more trades to comb through for the win and loss ratio and the average gain and loss.
Then, first on the SPY daily chart and later on a 5-minute chart over 5 days, I changed one thing at a time and read the P&L after each change:
- Turned off the short entries, then the long entries, to see which side drove the result.
- Moved consecutiveHistogramBars from 7 to 10, then down to 5.
- Moved the RSI levels from 60 and 40 to 70 and 30.
On the SPY daily chart over about 5 years, the short entries caused more of the losses, which makes sense with a bull run inside that window. I read out only P&L totals for the free version, without trade counts, so I don’t compare them here. Before you compare two totals of your own, check how many trades each report holds.
Free Version vs Member Version
The Squeeze histogram backtester in this tutorial measures P&L, and the member version adds the statistics. Volatility Box members have a version that puts the trade stats in labels on the chart. It’s included with the membership, with a tutorial on how it’s built, as part of the Squeeze Course. The course has a Histogram Pro Backtester module.
| Feature | Free download (this tutorial) | Member version (Squeeze Course) |
|---|---|---|
| Entries and exits | Momentum shifts on the histogram | Momentum shifts on the histogram |
| Long and short switches | Yes | Yes |
| Where the stats are | Floating P&L and Show report | Labels and strategy bubbles on the chart |
| Stats shown | Total P&L, trade list | Winners, losers, average win %, average loss %, average trade duration, per side |
Results From the Video
The Squeeze histogram results in the video come from the member version’s labels, which give winners and losers for each side. These are historical results from the charts loaded when I recorded, not a forecast, and most of the samples are small.
| Chart in the video | Period | Long side | Short side |
|---|---|---|---|
| S&P, 5-minute | 30 days | 12 winners, 32 losers | 17 winners, 23 losers |
| S&P, 5-minute | 5 days | Counts not read out | 9 winners, 1 loser |
| SPY, 5-minute | 5 days | 2 winners, 2 losers | 10 winners, 1 loser |
| Apple, 30-minute, extended hours off | 90 days | 4 winners, 4 losers | 1 winner, 10 losers |
On the SPY 5-day run, long trades lasted about 9.5 five-minute bars on average, about 50 minutes per trade. The short trades lasted a little longer, and the average short winner was much greater than the average short loser.
Apple’s 30-minute chart was basically the reverse of the S&P: the short side, the strongest side on the S&P, won 1 trade out of 11. The same rules behave differently on each market and timeframe, so test the one you trade.
How I Use the Backtester
The Squeeze histogram backtester is a starting point for research. With the free version, the work is manual: study the reports and look for the common patterns and tendencies. How many winners, how many losers, and is it the long or the short side driving the P&L?
- Test one side at a time. Turn longEntries or shortEntries off and compare.
- Change one input at a time. Bar count first, then the RSI levels, so you know what moved the result.
- Swap the filter. Replace the RSI with your own condition if another indicator fits your trading better.
The code has no stop loss. A trade stays open until the histogram turns, so before you trade a histogram shift, decide where your stop goes and size the position so a stop-out costs a small, fixed share of your account.
Related Squeeze Backtesters and Tools
The Squeeze histogram backtester tests one part of the Squeeze. These free tools cover other parts:
- The dots. Our Squeeze backtester trades 5 red dots in a row with stacked EMAs and lets you test the Squeeze settings.
- Squeezes inside a trend. The Trend Squeeze indicator plots an arrow when a squeeze, stacked moving averages and a 3/8 EMA cross line up.
- More strategies. Browse our free ThinkorSwim backtesters for other setups built with
AddOrder.
Common Problems
Most problems with the Squeeze histogram backtester come from where it was created or how strict the filters are.
- An error that the strategy should contain AddOrder. The editor shows it while no order lines exist. It goes away once the
AddOrderlines are in. - No orders on the chart. Check that you created it under the Strategies tab.
AddOrderworks only in a strategy. - No floating P&L graph. Turn on Display floating P&L with strategies in Global Strategy Settings.
- Very few trades. Each entry needs a full run of bars and an RSI reading on the right side of the threshold. Lower consecutiveHistogramBars or move the RSI levels closer to 50 for more trades, and check the report to see what changed.
TTM Squeeze Histogram Backtester.ts
#Written by TOS Indicators 2022
#Home of the Volatility Box
#Strategy: TTM Squeeze Histogram Backtester
#Full Tutorial Link: tosindicators.com/backtesters/ttm-squeeze-histogram
#Squeeze Course Link: tosindicators.com/squeeze-course

input consecutiveHistogramBars = 7;
input RSIOverboughtVal = 60;
input RSIOversoldVal = 40;
input longEntries = yes;
input shortEntries = yes;

def histogram = TTM_Squeeze().histogram;

#Cyan, Blue, Yellow and Red Histogram Bar Definitions
def cyan = histogram > histogram[1] and histogram > 0;
def blue = histogram < histogram[1] and histogram > 0;
def red = histogram < histogram[1] and histogram < 0;
def yellow = histogram > histogram[1] and histogram < 0;

#Consecutive Momentum Histogram Bars
def minCyanBars = Sum(cyan, consecutiveHistogramBars) >= consecutiveHistogramBars;
def minRedBars = Sum(red, consecutiveHistogramBars) >= consecutiveHistogramBars;

#Momentum Shifts in Histogram
def momoDown = minCyanBars[1] and blue;
def momoUp = minRedBars[1] and yellow;

#RSI
def RSIOverbought = RSI() > RSIOverboughtVal;
def RSIOversold = RSI() < RSIOversoldVal;

AddOrder(OrderType.Buy_To_Open, longEntries and momoUp and RSIOversold, close);
AddOrder(OrderType.Sell_To_Close, histogram < histogram[1], close);

AddOrder(OrderType.Sell_To_Open, shortEntries and momoDown and RSIOverbought, close);
AddOrder(OrderType.Buy_To_Close, histogram > histogram[1], close);
Want the .ts file and the one-click import? Both come with a free account.
Cyan is above zero and higher than the bar before, so bullish momentum is increasing. Blue is above zero and lower, so it's fading. Red is below zero and lower, so bearish momentum is increasing. Yellow is below zero and higher, so the selling momentum is fading.
It looks for a momentum shift after a run of one color. A long trade needs 7 red bars in a row, then a yellow bar, with the RSI below 40. A short trade needs 7 cyan bars in a row, then a blue bar, with the RSI above 60. Both enter at the bar's close.
A long trade exits at the close of the first bar where the histogram is lower than the bar before, and a short trade exits on the first bar where it's higher. The exit doesn't wait for a particular color, so a long can close on a red bar below zero.
Create a strategy: click the Studies icon, switch to the Strategies tab, click Create and paste in the code. Apply it to a chart, then right-click the strategy and choose Show report for the trade list. Turn on the floating P&L graph in Global Strategy Settings if you don't see it.
The RSI filters out some false signals. A long entry needs the RSI below 40 and a short entry needs it above 60, so the backtester only takes shifts after the market has moved one way. On a daily SPY chart in the video, the filter removed a number of the signals.
The member version's labels showed 12 winners and 32 losers long and 17 winners and 23 losers short on a 5-minute S&P chart over 30 days. On Apple's 30-minute chart over 90 days, longs had 4 winners and 4 losers and shorts had 1 winner and 10 losers. These are small historical samples.
Both trade the same histogram momentum shifts. The free version gives you the floating P&L and the Show report trade list. The member version adds labels with winners, losers, average win and loss percentages and average trade duration for each side. It's part of the Squeeze Course, with a tutorial on how it's built.
Yes. The longEntries and shortEntries inputs both default to yes. Set either one to no in the strategy's settings and the P&L shows only the other side. In the video I used them to see which side was causing more of the losses.
Ready to Trade With an Edge?
Join 40,000+ traders using institutional-grade tools for ThinkOrSwim.
Get the Bundle